Can You Stop a Foreclosure in Tennessee?
Can You Stop a Foreclosure in Tennessee?
If you're worried about losing your home, understanding your options and acting promptly can make a difference. Here's how to get oriented, what to ask your mortgage servicer, and where to find reliable help.

Usa el selector de idioma en la parte superior para traducir la página al instante, o comunícate con nuestro equipo para consultar opciones de asesoría bilingüe.

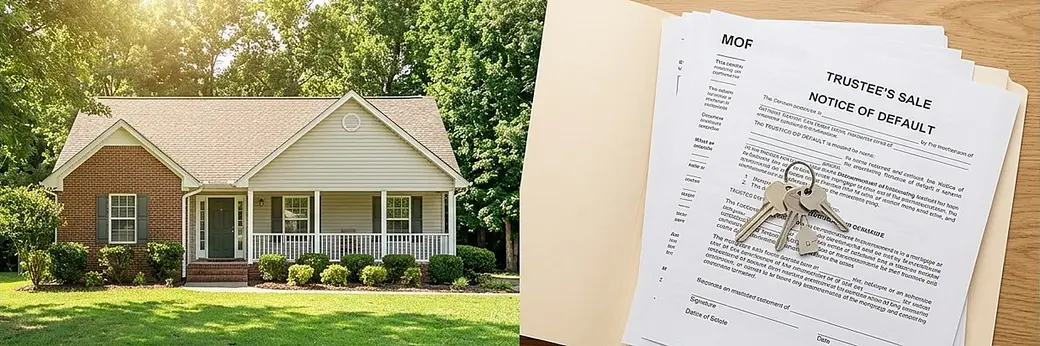
If you've received a notice that your home may be headed toward foreclosure in Tennessee, don't ignore it. You may have options, but the steps available to you depend on your loan, the notices you've received, and how far the process has progressed.
This guide provides general information, not legal advice. For guidance about your specific deadline or rights, contact your mortgage servicer, a HUD-approved housing counselor, or a Tennessee foreclosure attorney.
How Much Time Do You Have Before a Tennessee Foreclosure Sale?
Tennessee commonly uses nonjudicial foreclosure, meaning a lender may proceed under a power-of-sale provision in the mortgage or deed of trust without filing a traditional foreclosure lawsuit. The required notices and timeline can vary by loan, property, and circumstances.
Missed Payment
Contact your mortgage servicer as early as possible. Ask about repayment arrangements and loss-mitigation options, and keep a record of every conversation.
Default or Foreclosure Notice
Review each notice and its deadlines. Ask the servicer to explain the next steps in writing and seek housing or legal counseling promptly.
Sale Date Scheduled
Treat the date as urgent. Ask immediately whether any option remains available before the sale, and speak with a qualified professional about your circumstances.
Can Catching Up on Payments Stop a Foreclosure?
Possibly. In some situations, paying the amount required to bring a loan current, often called reinstatement, may stop the process if it is completed before the applicable deadline. The amount can include missed payments, fees, and other charges allowed under the loan terms.
Contact your servicer and request a written reinstatement quote that states the amount due and the date through which it is valid. Do not assume that making a partial payment will pause a scheduled sale unless the servicer confirms the arrangement in writing.

What Options May Exist Besides Paying Everything at Once?
Depending on your loan and financial situation, you may be able to ask your servicer about one or more of these options. Eligibility and timing vary, and none is guaranteed.
A short sale requires lender approval and may have financial or tax consequences. If you're considering one, discuss your circumstances with your mortgage servicer and a qualified attorney or tax professional before making a decision.
Where Can You Get Help With a Tennessee Foreclosure?
Start with your mortgage servicer, but don't stop there if you need help understanding your choices. HUD-approved housing counselors can explain available resources and help you prepare for conversations with your servicer.
Tennessee Housing Development Agency (THDA)
THDA provides foreclosure-prevention information and can connect homeowners with housing counseling resources. Counseling is available at no cost through its HUD-certified counselors.
Phone: 1-888-483-8432 or 615-815-2238
Visit THDA's Foreclosure Prevention page
Find additional homeowner and legal-help resources through Help4TN
| Common Homeowner Assumptions | What to Keep in Mind |
|---|---|
| “If I miss a payment, foreclosure is inevitable.” | Depending on your situation, options may be available. Contact your servicer early and ask about loss mitigation. |
| “I have plenty of time to figure things out later.” | Deadlines vary, and formal foreclosure steps can move quickly. Read every notice and verify the dates that apply to you. |
| “My only choices are paying everything in full or losing the house.” | Ask about repayment plans, loan modification, forbearance, or sale options. Eligibility and consequences differ. |
Frequently Asked Questions
Can I stop a foreclosure in Tennessee if I catch up on payments?
It may be possible, depending on the loan terms and where the process stands. Request a written reinstatement amount and deadline from your mortgage servicer right away.
How fast can foreclosure happen in Tennessee?
The timeline depends on the loan, required notices, and individual circumstances. Some cases move quickly after formal steps begin, so don't rely on a general estimate for your own deadline.
What does loss mitigation mean?
Loss mitigation refers to options a mortgage servicer may consider to address delinquency and avoid foreclosure, such as repayment plans, loan modifications, or forbearance.
Can a short sale help if I am facing foreclosure?
A lender-approved short sale may be an option in some circumstances, but it is not guaranteed to stop a scheduled sale automatically. Work with your servicer and qualified legal or tax professionals to understand the timing and consequences.
Need Help Understanding Your Home-Sale Options?
If selling your property or exploring a short sale may be part of your plan, Isabel Pirela can help you understand the real estate side of the process and discuss possible next steps. For legal deadlines or foreclosure rights, speak with a Tennessee attorney or HUD-approved housing counselor.
Request a MeetingThis article is educational and does not create an attorney-client relationship. Foreclosure procedures and available options vary. Verify current requirements and seek professional advice for your specific situation.
Categories
Recent Posts